
The changes to Agricultural Property Relief and Business Property Relief announced in October 2024 start on 6 April 2026. They've been softened since, so here's where things stand.
The new allowance
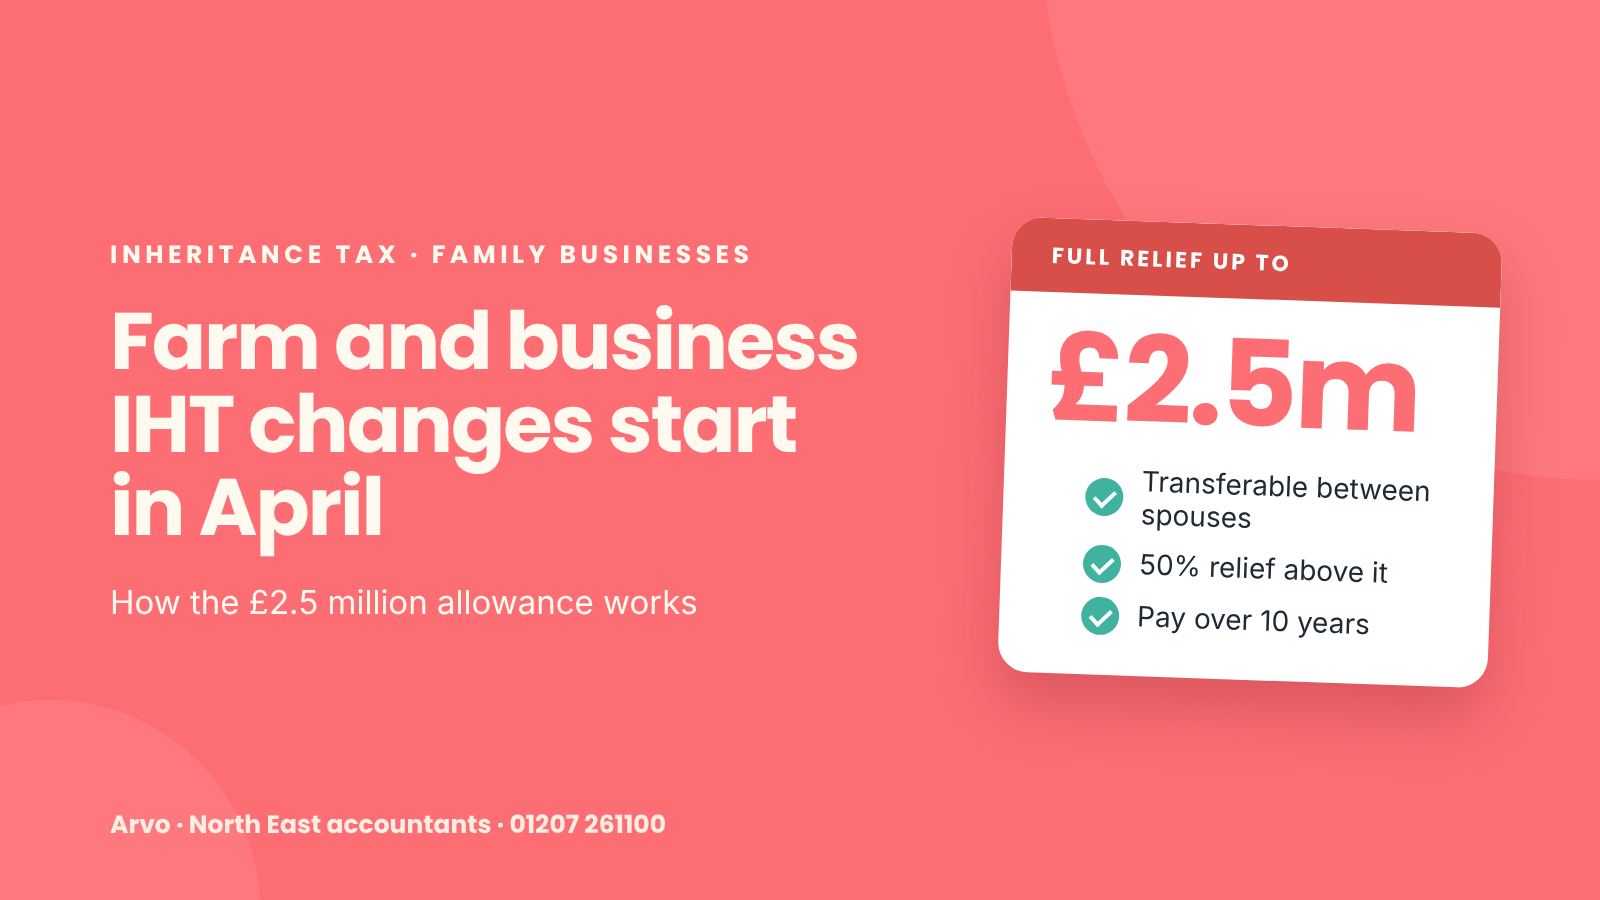
100% relief applies to the first £2.5 million of combined business and agricultural property. This was raised from the £1 million originally announced
Above the allowance, relief is 50%, giving an effective inheritance tax rate of 20% on the excess
Any unused allowance can be transferred to a surviving spouse or civil partner, so a couple could pass on up to £5 million with full relief
Shares on AIM
Shares on AIM and similar markets get 50% relief, rather than 100%.
Paying the tax
Inheritance tax on qualifying business and agricultural property can be paid in 10 annual instalments, interest-free. That helps families avoid selling land or the business to pay the bill.
An example
A widow inherits her husband's unused allowance, and leaves a farm worth £6 million to her children. With £5 million of allowances, £1 million gets 50% relief, so £500,000 is taxable. At 40%, that's £200,000, which could be paid over 10 years. Other nil-rate bands may reduce it further.
What to review now
Get up-to-date valuations of the business, land and buildings
Check your will. Make sure it uses both spouses' allowances
Consider lifetime gifts. Gifts are usually free of inheritance tax if you live for seven years
Think about liquidity. Could the next generation pay the tax?
Look at the whole estate, including the new rules on pensions from April 2027
Related reads
Business Asset Disposal Relief rises to 18% in April: last chance at 14%
Passing on the family business: planning for the next generation
How Arvo can help
We can help you understand your position under the new rules and work with your solicitor and financial adviser on a plan.
Get in touch to arrange a free, no-obligation chat, or call us on 01207 261100.